Good Piece of Information from TheStar :-
LATELY, as a result of better stock-market sentiment, investors are starting to pay attention to warrants. With their prices relatively lower than that of mother shares, warrants are viewed as an alternative to achieving higher returns and providing cheaper entry to the mother shares.
What is a warrant?
A warrant is a transferrable option certificate issued by a company that entitles the holder to buy a specific number of shares in that company at a specific price (or exercise price) at a specified time in the future.
Normally, a company issues warrants together with bonds to raise capital. Because investors can detach the warrants and sell them separately to get some returns, the coupon rates for these bonds will be lower.
As a result, we can treat this as a “sweetener” for investors to attract them to buy into lower coupon-rate bonds. Besides, capital raising through warrants will be less disruptive to a company’s earnings as investors are given a certain period to exercise their rights.
The intrinsic value of a warrant is the value that an investor will get if the warrant were to be exercised immediately. It is the difference between the price of the mother share and the exercise price.
A positive intrinsic value means the warrant is “in-the-money” and the investor may exercise his rights now given that he can buy the mother share at a cheaper price. A negative intrinsic value means the warrant is “out-of-money” and the investor will not exercise his rights as he has to pay higher than the current market price for the mother share.
Usually, warrants are traded at a premium because investors are willing to pay extra for the benefits that warrants offer. However, investors need to know the premium that they are paying. Premium can be computed based on the following formula:
PREMIUM (%) = (WARRANT + EXERCISE PRICE – SHARE PRICE)/SHARE PRICE X 100
For example, if Company A’s share price is RM4.50 and the exercise price is RM3.75, Company A’s warrant (Company A-W) price of RM1.36 will imply a premium of 13.6%.
Premium = (1.36 + 3.75 – 4.50)/4.50 x 100 = 13.6%.
For any given warrant, the higher the premium, the more expensive the warrant becomes. If an investor pays a premium to buy a warrant, the underlying share must rise by a percentage equal to the premium before the maturity date to break even.
The main reason for the preference shown by investors in buying warrants instead of their mother shares is the gearing factor. It is computed by dividing the mother share price by warrant price.
Based on the above example, the gearing factor for Company A-W is 3.31 times (4.50/1.36). It means that by buying into Company A-W instead of Company A (with the same amount of investment), the exposure to Company A is 3.31 times larger than investing in Company A (the mother share) itself.
Hence, due to the lower price relative to the price of the mother share, gearing can show how many times a warrant is able to outperform or under-perform versus the mother share.
Capital Fulcrum Point (CFP)
CFP combines premium and time-to-maturity to provide a compound indicator. It can be interpreted as the average percentage increase in the price of the mother share per year assuming all other factors remain constant.
It is computed based on the following formula:
CFP = [{EXERCISE PRICE/(SHARE PRICE – WARRANT PRICE)} ^ (1/Y) – 1] X 100
Where y = the remaining years-to-maturity, ^ means to the power of
Based on the above example, if y = 5.82 years, CFP for Company A-W = [{3.75/(4.50 – 1.36)} ^ (1/5.82) – 1] x 100 = 3.1%.
It means that if Company A is able to grow by at least 3.1% a year, it will be cheaper to buy Company A-W than investing in Company A’s mother share.
In short, we can consider this CFP as taking the premium divided by the remaining time-to-maturity. When we take the above 13.6% premium and divide by 5.82 years, we will get 2.34%. Even though we cannot get the actual CFP, 2.34% can provide us with a close approximation to the correct CFP of 3.10%.
Due to the gearing factor, even though investors can get higher returns by investing in warrants instead of buying the mother shares, we need to understand the risks involved. Investors need to be extra careful when buying into warrants, especially those that are near their maturity.
Investors need to exercise the warrants or sell them into the market before the maturity dates because the warrants will become worthless after those dates.
Wednesday, June 3, 2009
Saturday, May 30, 2009
OIL & GAS FABRICATOR PANTECH GROUP 4QE FEB 2009 NET PROFIT HIGHER

CLASSIFICATION: ACCOUNTING/AUDIT NOTIFICATION/ANALYSIS & BUSINESS PROJECTIONS
TYPE: Short Analysis / Reviews
13 May 2009
OIL & GAS FABRICATOR PANTECH GROUP 4QE FEB 2009 NET PROFIT HIGHER PANTECH GROUP HOLDINGS recorded marginally higher Net Profit of RM8.7m for 4QE Feb 28, 2009 compared with RM8.2m a year earlier despite Revenue surging 84% to RM139.3m from RM75.7m.
The Net Profit included a Provision of Stock Writedown of RM9.2m.
FULL FYE FEB 2009 RESULTS SHOW HIGHER PROFIT
Full FYE Feb 2009 was boosted to RM511.2m from RM313.3m compared with the previous year. PANTECH said Apr 27, 2009 that its full-year Net Profit jumped 75% to RM59.6m from RM34.1m in the previous year due to higher manufacturing output, higher sales volume, better product mix from the trading division and contribution from overseas operation.
FINAL SINGLE-TIER DIVIDEND PROPOSED
The Company proposed a final single-tier dividend of one sen per share totalling RM3.7m, bringing Total Dividend for FYE Feb 2009 to three sen per share. EPS to 15.94 sen from 9.1 sen, while Net Assets per share increased to 53 sen from 39 sen.
PROSPECT FOR 2009
On prospects for the current financial year, the Company said the duration, extent and impact of the persisting global financial meltdown were uncertain.
" .... Therefore, the Board will adopt a cautious approach to monitor the situation and mitigate any negative impact through diligent administration of operation cost controls and cash flows .... In view of the above, the board foresees the next financial year will be a challenging year for the Group ...." it said, adding that the Group's performance for the next financial year would be in line with the overall performance of the oil and gas fabrication and other services sector while the long-term outlook continued to be positive.
TARGET PRICE = 0.85sen
Friday, May 29, 2009
HUAAN result differ!? Computer Glitch on Financial Result ??
There seem to have some problem with the financial result with the online trading system comparing with annoucement from Bursa website :-
Below is captured from my trading system :-

This is from Bursa Website :-

Obviously HUAAN is running into loss of EPS = -2.11 for this quarter but what captured from the trading system is in positive zone. Misleading !!
Likely that this gonna affect the entire financial annoucements, so be careful folk when you searching for financial result, cross check with bursa's website for it accuracy.
Below is captured from my trading system :-

This is from Bursa Website :-

Obviously HUAAN is running into loss of EPS = -2.11 for this quarter but what captured from the trading system is in positive zone. Misleading !!
Likely that this gonna affect the entire financial annoucements, so be careful folk when you searching for financial result, cross check with bursa's website for it accuracy.
Monday, May 25, 2009
Received 10sen Dividend From GUINNESS
Just gotten myself a 10sen tax exempted dividend from GUINNESS. So far never failed to receive dividend from this liquor company.
Wednesday, May 20, 2009
Sold Maybank at RM5.15 & Received Dividend from CARLSBERG & Maybulk
Sold all my Maybank at RM5.15 again & just received dividend from Carlsbg & Maybulk.


Tuesday, May 19, 2009
Sold Maybank @ RM5.15
Just sold off all MAYBANK holding at RM5.15 :-

Received BJTOTO's 3rd interim dividend of 5sen. Every quarter i strike a consolation prize on this, hahaha, better than buying 4 ekor...
Bought back MAYBANK at RM5.05 and make intraday gain for the order sold this morning at RM5.15. Still holding same amount of MAYBANK shares at RM5.00.

Received BJTOTO's 3rd interim dividend of 5sen. Every quarter i strike a consolation prize on this, hahaha, better than buying 4 ekor...
Bought back MAYBANK at RM5.05 and make intraday gain for the order sold this morning at RM5.15. Still holding same amount of MAYBANK shares at RM5.00.
Wednesday, May 13, 2009
Bought Back MAYBANK
Bought back Maybank at RM5. Would likely hold this as longterm if market turn south. Playing with bluechip still give me sense of safety than exposing yourself on a much volatile 3rd liners or penny stocks.
Tuesday, May 12, 2009
Intraday Gain on PBBANK-01
Just manage to make a quick intraday gain on PBBANK-01, bought them at RM8.4 and sold them at RM8.5....

Sold all TM....


Sold all TM....

Thursday, May 7, 2009
Did a quick scalp on Maybank
Bought Maybank early in the morning at RM5 and sold all of them at RM5.10. A quick hit and run while seeing the market surging high. There you go seize the opportunity if you can in this 'bully' bull.....


Friday, April 24, 2009
Scalp on SAAG
Did a quick scalp on SAAG when seeing the opportunity by buying at RM0.24 and disposing them in stages up. Making some quick bucks for weekend money.


Sold All My Maybulk
Just sold off all my Maybulk this morning at RM3.02 after ex-date of 30sen dividend. The reason of selling is simple, i expect EPS for year 2009 to fall and might expect a lower net dividend payout for Maybulk after a generous 30sen div. Thus, trigger my selling idea for now. Will keep monitor this counter until there is clearer earning expected before getting it back.
Meanwhile take a look of it financial summary below:-

Meanwhile take a look of it financial summary below:-

Thursday, April 16, 2009
Sold Half of Zhulian at RM1.14
Manage to dispose half of my holding on ZHULIAN. ZHULIAN has just declared a 1st interim ST dividend of 3sen. ZHULIAN has been giving out dividend on every quarter without failed. Annual % return on div is about 10% based on current price at 1.14. Long term hold and beating FD rate of 3% is anytime from ZHULIAN.....
Take a look of its div payout so far....
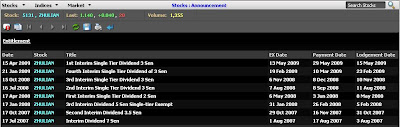
Take a look of its div payout so far....

Wednesday, April 15, 2009

Wednesday, April 8, 2009
More Investors Say Bye-Bye to Buy-and-Hold
Interesting Article, hng, for your reading pleasure.....
By JANE J. KIM
For much of the past decade, Kenneth Kimmons of Bedford, Texas, was a buy-and-hold investor. He regularly socked away money in mutual funds across his 401(k) plans, individual retirement accounts and a brokerage account.
But after watching his investments fall by about 50% last year, he started trading individual stocks and options full-time last fall. He generally buys stocks at the start of the trading day -- lately, it's been bank stocks -- and sells them a few hours later. "I just got tired of putting money away and losing it," says the 31-year-old. He says he's doubled his money since he started trading full-time.
The ups and downs of the market are prompting more retail investors to abandon buy-and-hold strategies in favor of opportunistic trading. Some want more control over their money, so they are fleeing funds and advisers -- not to mention the feelings of helplessness raised by recent months' losses. Some are attempting to recoup their losses, while others are stepping back into the markets after a recent string of stock gains and better-than-expected economic news.
Most financial advisers still believe investors should stay the course, pointing out that frequent trading can incur fees, erode returns and result in higher tax bills. But many individuals have lost faith in the long-term growth of their investments and are trying to make money off the market's volatility.
"When I was younger, I banked on the fact that, over time, stocks will go up, and that if you dollar-cost average [following a fixed schedule of purchases], you'll be fine," says Jim Catalano of Ashburn, Va., who in September rolled over money from an old 401(k) into an IRA at TradeKing, an online brokerage firm with low trading fees. "But my time horizon is getting shorter -- and when you see your 401(k) get chopped in half, I decided I needed to take the reins here and not leave it to the money managers."
Mr. Catalano trades mostly stocks and exchange-traded funds, usually four to five times a week. He writes covered-call option contracts to generate income off his shares, a tactic that could lose him some of the upside if share prices rise substantially. Since he started trading in September, he is down about 5% but has done better than the market.
At the New York Stock Exchange and Nasdaq stock exchanges, turnover levels -- a measure of how often the average share changes hands -- have been rising. At the same time, stock-fund investors sold about 33% of their holdings last year, implying a three-year average holding period, down from a four-year holding period in 2004, according to the Bogle Financial Markets Research Center.
Discount brokerage firms -- including Charles Schwab Corp., TD Ameritrade Holding Corp., E*Trade Financial Corp., ING Groep NV's Sharebuilder and Fidelity Investments -- are seeing record levels of trading activity and new-account openings. Since last September, nearly 7.5 million investors -- or 20% of the online investing community -- have increased trading volume enough to be temporarily reclassified at a higher trading level, says Matthew Bienfang, senior research director at TowerGroup.
More Investors Ramp Up Trading
More buy-and-hold investors are changing tactics. Here are some factors to consider:
Trading activity and new account openings are hitting highs as average holding periods decline.More investors are trying to take advantage of market volatility, which they expect to continue.Active trading can erode returns as investors get hit with higher trading costs and taxes."Typically in a bear market, you'll see a retraction of activity and reduction of people opening new accounts," says Jay Pestrichelli, managing director at TD Ameritrade. "This time around, somebody forgot to tell the retail client that's what happens."
Some market experts say retail investors are likely to make a bad situation even worse. "It's a fools' game," says John Bogle, the 79-year-old founder of mutual-fund giant Vanguard Group, which helped popularize index funds and the virtues of buy-and-hold investing. Not only will short-term investors pay more commissions, fees and other costs, but various studies have shown that market timers typically lose more money than buy-and-hold investors. "If you want to trade the market, you've got to be right twice -- you've got to get out and get back in," he says.
But others say things are different this time. "The problem I have with the buy-and-hold strategy is that it's a bull-market strategy," say Matthew Tuttle, a financial adviser in Stamford, Conn. "In the bust, you give all of your profits back." Mr. Tuttle has recently taken a more active approach to trading. While short-term investors are likely to face higher tax bills -- since short-term gains are taxed at higher rates than long-term gains -- he notes that some people who incurred big losses last year will be able to carry those losses forward to offset taxes in future years.
"The psychology of the market is broken," says Michael Parness, who runs Trendfund.com, which dispenses trading advice online. "People just don't trust it." As a result, many of the market's moves are "almost entirely based on whatever news is coming out of the government," he says.
The uncertain environment has prompted David Dilley of Bonita Springs, Fla., to trade more frequently. The 76-year-old retiree believes there has been a "sea change" in economic philosophy -- shifting from private enterprise to a command-and-control economy. "The long-term market gains that we've had in the past will not occur until that reverts and we get back free enterprise," he says. So, while he had considered himself a longtime buy-and-hold investor, he's now trading Canadian oil trusts in his E*Trade account several times a week. Mr. Dilley didn't provide exact numbers but says he's beating the broader market averages so far this year.
In another sign that investors are getting more speculative, the most widely held stocks in investors' accounts at discount brokerage firms Sharebuilder, TradeKing and Firstrade Securities Inc. are the same ones that are under the most pressure, including Citigroup Inc., American International Group Inc., Ford Motor Co., General Electric Co., and Bank of America Corp. By contrast, the most popular stocks a year ago were Apple Inc., Google Inc., Microsoft Corp. and the like.
"We see a lot of people trying to ride the waves of stocks with no long-term vision," says TradeKing Chief Executive Don Montanaro. "They're so low-priced -- and it's nothing for these stocks to move 40% or 50% in a week."
Sue Cirillo of Pelham Manor, N.Y., used to hold on to household names such as Apple. But last fall, she sold some of her longtime holdings, moved to cash and started trading. "The difference between now and then is that when I've made money, I take it off the table and look for the next opportunity," says the 47-year-old music producer. "Before, I was more focused on companies that I felt were going to be profitable." Now, she pays attention to daily market swings, subscribes to online advice services such as Mr. Parness's for trading ideas, and has recently learned to short stocks.
Mark Swenson of southern New Hampshire says he typically trades with exchange-traded funds, instead of buying individual stocks. The 40-year-old says he started trading for the first time last October, in part to generate additional income in case his work as a plumber dried up. Although he says he got "slaughtered" when he first started trading, he says that he has since made up much of that initial loss and that it's easier for him to trade than do nothing.
"I could no longer stomach it -- watching my money disappear," he says. "For right now, it's a traders' market. Until I get the sense that the market is on the rise, I generally don't plan on doing any buying and holding -- not for the long term."
Others got tired of paying their advisers. Last June, Linda Smith of Denver fired her broker, saying it was a waste of money to pay her adviser 1.5% in annual fees for picking mutual funds she believed she could pick herself. "No one on this planet knows better what to do with my finances than me," says the 53-year-old.
For the year, she figures her portfolio is up about 5%, including the interest from her CDs. "Nobody can time the market 100% correctly 100% of the time," she says. "However, that doesn't mean you can't get lucky now and then."
By JANE J. KIM
For much of the past decade, Kenneth Kimmons of Bedford, Texas, was a buy-and-hold investor. He regularly socked away money in mutual funds across his 401(k) plans, individual retirement accounts and a brokerage account.
But after watching his investments fall by about 50% last year, he started trading individual stocks and options full-time last fall. He generally buys stocks at the start of the trading day -- lately, it's been bank stocks -- and sells them a few hours later. "I just got tired of putting money away and losing it," says the 31-year-old. He says he's doubled his money since he started trading full-time.
The ups and downs of the market are prompting more retail investors to abandon buy-and-hold strategies in favor of opportunistic trading. Some want more control over their money, so they are fleeing funds and advisers -- not to mention the feelings of helplessness raised by recent months' losses. Some are attempting to recoup their losses, while others are stepping back into the markets after a recent string of stock gains and better-than-expected economic news.
Most financial advisers still believe investors should stay the course, pointing out that frequent trading can incur fees, erode returns and result in higher tax bills. But many individuals have lost faith in the long-term growth of their investments and are trying to make money off the market's volatility.
"When I was younger, I banked on the fact that, over time, stocks will go up, and that if you dollar-cost average [following a fixed schedule of purchases], you'll be fine," says Jim Catalano of Ashburn, Va., who in September rolled over money from an old 401(k) into an IRA at TradeKing, an online brokerage firm with low trading fees. "But my time horizon is getting shorter -- and when you see your 401(k) get chopped in half, I decided I needed to take the reins here and not leave it to the money managers."
Mr. Catalano trades mostly stocks and exchange-traded funds, usually four to five times a week. He writes covered-call option contracts to generate income off his shares, a tactic that could lose him some of the upside if share prices rise substantially. Since he started trading in September, he is down about 5% but has done better than the market.
At the New York Stock Exchange and Nasdaq stock exchanges, turnover levels -- a measure of how often the average share changes hands -- have been rising. At the same time, stock-fund investors sold about 33% of their holdings last year, implying a three-year average holding period, down from a four-year holding period in 2004, according to the Bogle Financial Markets Research Center.
Discount brokerage firms -- including Charles Schwab Corp., TD Ameritrade Holding Corp., E*Trade Financial Corp., ING Groep NV's Sharebuilder and Fidelity Investments -- are seeing record levels of trading activity and new-account openings. Since last September, nearly 7.5 million investors -- or 20% of the online investing community -- have increased trading volume enough to be temporarily reclassified at a higher trading level, says Matthew Bienfang, senior research director at TowerGroup.
More Investors Ramp Up Trading
More buy-and-hold investors are changing tactics. Here are some factors to consider:
Trading activity and new account openings are hitting highs as average holding periods decline.More investors are trying to take advantage of market volatility, which they expect to continue.Active trading can erode returns as investors get hit with higher trading costs and taxes."Typically in a bear market, you'll see a retraction of activity and reduction of people opening new accounts," says Jay Pestrichelli, managing director at TD Ameritrade. "This time around, somebody forgot to tell the retail client that's what happens."
Some market experts say retail investors are likely to make a bad situation even worse. "It's a fools' game," says John Bogle, the 79-year-old founder of mutual-fund giant Vanguard Group, which helped popularize index funds and the virtues of buy-and-hold investing. Not only will short-term investors pay more commissions, fees and other costs, but various studies have shown that market timers typically lose more money than buy-and-hold investors. "If you want to trade the market, you've got to be right twice -- you've got to get out and get back in," he says.
But others say things are different this time. "The problem I have with the buy-and-hold strategy is that it's a bull-market strategy," say Matthew Tuttle, a financial adviser in Stamford, Conn. "In the bust, you give all of your profits back." Mr. Tuttle has recently taken a more active approach to trading. While short-term investors are likely to face higher tax bills -- since short-term gains are taxed at higher rates than long-term gains -- he notes that some people who incurred big losses last year will be able to carry those losses forward to offset taxes in future years.
"The psychology of the market is broken," says Michael Parness, who runs Trendfund.com, which dispenses trading advice online. "People just don't trust it." As a result, many of the market's moves are "almost entirely based on whatever news is coming out of the government," he says.
The uncertain environment has prompted David Dilley of Bonita Springs, Fla., to trade more frequently. The 76-year-old retiree believes there has been a "sea change" in economic philosophy -- shifting from private enterprise to a command-and-control economy. "The long-term market gains that we've had in the past will not occur until that reverts and we get back free enterprise," he says. So, while he had considered himself a longtime buy-and-hold investor, he's now trading Canadian oil trusts in his E*Trade account several times a week. Mr. Dilley didn't provide exact numbers but says he's beating the broader market averages so far this year.
In another sign that investors are getting more speculative, the most widely held stocks in investors' accounts at discount brokerage firms Sharebuilder, TradeKing and Firstrade Securities Inc. are the same ones that are under the most pressure, including Citigroup Inc., American International Group Inc., Ford Motor Co., General Electric Co., and Bank of America Corp. By contrast, the most popular stocks a year ago were Apple Inc., Google Inc., Microsoft Corp. and the like.
"We see a lot of people trying to ride the waves of stocks with no long-term vision," says TradeKing Chief Executive Don Montanaro. "They're so low-priced -- and it's nothing for these stocks to move 40% or 50% in a week."
Sue Cirillo of Pelham Manor, N.Y., used to hold on to household names such as Apple. But last fall, she sold some of her longtime holdings, moved to cash and started trading. "The difference between now and then is that when I've made money, I take it off the table and look for the next opportunity," says the 47-year-old music producer. "Before, I was more focused on companies that I felt were going to be profitable." Now, she pays attention to daily market swings, subscribes to online advice services such as Mr. Parness's for trading ideas, and has recently learned to short stocks.
Mark Swenson of southern New Hampshire says he typically trades with exchange-traded funds, instead of buying individual stocks. The 40-year-old says he started trading for the first time last October, in part to generate additional income in case his work as a plumber dried up. Although he says he got "slaughtered" when he first started trading, he says that he has since made up much of that initial loss and that it's easier for him to trade than do nothing.
"I could no longer stomach it -- watching my money disappear," he says. "For right now, it's a traders' market. Until I get the sense that the market is on the rise, I generally don't plan on doing any buying and holding -- not for the long term."
Others got tired of paying their advisers. Last June, Linda Smith of Denver fired her broker, saying it was a waste of money to pay her adviser 1.5% in annual fees for picking mutual funds she believed she could pick herself. "No one on this planet knows better what to do with my finances than me," says the 53-year-old.
For the year, she figures her portfolio is up about 5%, including the interest from her CDs. "Nobody can time the market 100% correctly 100% of the time," she says. "However, that doesn't mean you can't get lucky now and then."
Wednesday, March 25, 2009
Swapping PBB-F back to PBBANK again
Have managed to swap all my PBBANK-F at a price of RM7.55 to PBBANK at RM7.40, this is the similar swapping that i did previously in last December08 by swapping from PBB to PBB-F when there is margin of profit. Now i just did it the other way round (swapped PBB-F for PBB). Of course by doing so will in turn giving some contra money to me (the price different between both shares). Will repeat the same method if PBB price surpassing PBB-F in near future.
Tuesday, March 24, 2009

A behaviourial reminder
Making your money work
By JOYCE CHUAH
Pitfalls to avoid when making an investment.
LET’S face it. No investment decision will be right all the time. It is through wrong investment decisions that we make the right decisions eventually. So it is important to discuss some of the reasons why investments fail.
Often, emotional response is the culprit behind bad investment decisions. One of the most common emotional responses is the herd mentality. It is easy to follow the herd. We prefer to chase after the most talked about stocks, or follow the latest investment “guru”. When trouble looms, the herd mentality often kicks in. When everyone else is nervous about the market, so are we. We forget about our investment strategies, preferring to run instead of holding on for long-term returns.
Following the herd will mean you need to change course each time, and this will take you longer to reach your goal.
So what can you do? Draw up your own investment philosophy. Investment philosophies are like promises you want to make to yourself and investment behaviours you wish to inculcate.
Here are 10 of the most common investment mistakes:
1. Investing at the peak of an economic cycle.
It is always easier to invest when everything looks rosy, when confidence is high and your friends tell you they are making money. Worse of all, when you join in the fray, the bubble bursts. So what do you do? You decide to stay out and let the investment value ride back up to recoup your capital. The problem is if you invested at the peak of the cycle, it may be another five to eight years’ time before you see it peak again.
2. Taking advice from an “accurate source.”
Most investment losses can be attributed to following third party “hot tips” and advice without doing homework. Some even claim they had insider information or that the news came from the horse’s mouth. If it sounds too good to be true, it usually isn’t true!
3. Afraid to value cost when returns are negative.
Value cost averaging is one strategy to average your cost and lower your investment’s break-even point. For this strategy to work, you must have enough funds to value cost, give your investment vehicle enough time to come back up again, and most importantly, your investment vehicle must have the capability to rise in value eventually.
This strategy is useful in investments which are diversified in nature, like managed funds, as they will not lose all of their value even in the worst market scenario. If you are investing in stocks with good value prospects, be prepared to value average too.
4. Unaware of the status of investments.
Many investors know exactly when their fixed deposits are maturing but have no idea when it comes to their more volatile and growth-oriented investments. Investments must be tracked more regularly than fixed income vehicles and knowing their value and how they have performed over time helps you to seize opportunities to sell or accumulate more for value averaging purposes. However, do not monitor your investments too frequently as it can cause you to panic and sell your winners too soon.
5. Not having a required rate of return.
Investors often do not set a target of return for their investments. Even if they do, they shift their targets as greed sets in, especially in a bullish market. This can be dangerous as a sudden event in the market can wipe out profits. What one needs to do in a bullish market is to sell the profits when the desired rate of return is met and continue to monitor the capital for further market upsides. However, if you are a new or conservative investor, it is be better to realise both your profits and capital once your “triple R” (Required Rate of Return) is met.
6. Not rebalancing portfolios.
During the 2003 Iraq war, an investor announced that his investment planner had told him to switch his equity portfolios to bonds as the war could be a potential danger to his exposure to equities. I met the same investor again at the end of 2003. He said he had lost about 15% in his bond investments in the 2003 bond market crash.
Unfortunately for him, rebalancing portfolios was done as a single isolated event. He had forgotten that rebalancing must be done consistently in different cycles under which the specific investments are exposed to. My advice is to rebalance at the most twice a year, unless a sudden unexpected event happens.
7. Focus on popular investments.
Investors feel better when they invest in investments which have been highly publicised, advertised or the ones everyone else is getting into. Some of these are good investments and are worth looking into but do your homework. Check if they suit your investment goals and time-frame.
8. Focusing on “guaranteed” investments.
Having your capital guaranteed is fine but you need to realise what they are “guaranteeing” – capital or returns? This promise of “capital guarantee” usually deceives us in our understanding of balancing the cost of other investment opportunities during the holding period against the security of not losing our capital at the end of the tenure. Putting money into a guaranteed fund is only suitable if you do not need the funds within the holding period and you have a diversified investment portfolio.
9. Not having an investment philosophy.
An investment philosophy is just a simple statement of your investment style, what allocations you have determined for your investments, which investments you want to include in your portfolio and those you do not want to be included at all. The statement also outlines your purpose in investing, strategies to be undertaken should your investments go wrong, and the time-frame you have set aside for each investment. Your philosophy can be adjusted to suit the current scenario. Having an investment philosophy prevents us from being overly-greedy or overly fearful.
10. Transactional type of investments.
For most of us, the only purpose we invest is to make money. After that, what next? We need to have a purpose for our investments. Why did we invest in stocks, unit trusts and property? To make money? Yes, but what’s the purpose behind that purpose? Your investments must be purpose-driven, for example, to clear debts, fund a comfortable retirement, or to send your kids to college. Remember, greed is not a purpose.
Joyce Chuah is a Financial Intelligence trainer and Certified Financial Planner who has been in the industry for 10 years.
By JOYCE CHUAH
Pitfalls to avoid when making an investment.
LET’S face it. No investment decision will be right all the time. It is through wrong investment decisions that we make the right decisions eventually. So it is important to discuss some of the reasons why investments fail.
Often, emotional response is the culprit behind bad investment decisions. One of the most common emotional responses is the herd mentality. It is easy to follow the herd. We prefer to chase after the most talked about stocks, or follow the latest investment “guru”. When trouble looms, the herd mentality often kicks in. When everyone else is nervous about the market, so are we. We forget about our investment strategies, preferring to run instead of holding on for long-term returns.
Following the herd will mean you need to change course each time, and this will take you longer to reach your goal.
So what can you do? Draw up your own investment philosophy. Investment philosophies are like promises you want to make to yourself and investment behaviours you wish to inculcate.
Here are 10 of the most common investment mistakes:
1. Investing at the peak of an economic cycle.
It is always easier to invest when everything looks rosy, when confidence is high and your friends tell you they are making money. Worse of all, when you join in the fray, the bubble bursts. So what do you do? You decide to stay out and let the investment value ride back up to recoup your capital. The problem is if you invested at the peak of the cycle, it may be another five to eight years’ time before you see it peak again.
2. Taking advice from an “accurate source.”
Most investment losses can be attributed to following third party “hot tips” and advice without doing homework. Some even claim they had insider information or that the news came from the horse’s mouth. If it sounds too good to be true, it usually isn’t true!
3. Afraid to value cost when returns are negative.
Value cost averaging is one strategy to average your cost and lower your investment’s break-even point. For this strategy to work, you must have enough funds to value cost, give your investment vehicle enough time to come back up again, and most importantly, your investment vehicle must have the capability to rise in value eventually.
This strategy is useful in investments which are diversified in nature, like managed funds, as they will not lose all of their value even in the worst market scenario. If you are investing in stocks with good value prospects, be prepared to value average too.
4. Unaware of the status of investments.
Many investors know exactly when their fixed deposits are maturing but have no idea when it comes to their more volatile and growth-oriented investments. Investments must be tracked more regularly than fixed income vehicles and knowing their value and how they have performed over time helps you to seize opportunities to sell or accumulate more for value averaging purposes. However, do not monitor your investments too frequently as it can cause you to panic and sell your winners too soon.
5. Not having a required rate of return.
Investors often do not set a target of return for their investments. Even if they do, they shift their targets as greed sets in, especially in a bullish market. This can be dangerous as a sudden event in the market can wipe out profits. What one needs to do in a bullish market is to sell the profits when the desired rate of return is met and continue to monitor the capital for further market upsides. However, if you are a new or conservative investor, it is be better to realise both your profits and capital once your “triple R” (Required Rate of Return) is met.
6. Not rebalancing portfolios.
During the 2003 Iraq war, an investor announced that his investment planner had told him to switch his equity portfolios to bonds as the war could be a potential danger to his exposure to equities. I met the same investor again at the end of 2003. He said he had lost about 15% in his bond investments in the 2003 bond market crash.
Unfortunately for him, rebalancing portfolios was done as a single isolated event. He had forgotten that rebalancing must be done consistently in different cycles under which the specific investments are exposed to. My advice is to rebalance at the most twice a year, unless a sudden unexpected event happens.
7. Focus on popular investments.
Investors feel better when they invest in investments which have been highly publicised, advertised or the ones everyone else is getting into. Some of these are good investments and are worth looking into but do your homework. Check if they suit your investment goals and time-frame.
8. Focusing on “guaranteed” investments.
Having your capital guaranteed is fine but you need to realise what they are “guaranteeing” – capital or returns? This promise of “capital guarantee” usually deceives us in our understanding of balancing the cost of other investment opportunities during the holding period against the security of not losing our capital at the end of the tenure. Putting money into a guaranteed fund is only suitable if you do not need the funds within the holding period and you have a diversified investment portfolio.
9. Not having an investment philosophy.
An investment philosophy is just a simple statement of your investment style, what allocations you have determined for your investments, which investments you want to include in your portfolio and those you do not want to be included at all. The statement also outlines your purpose in investing, strategies to be undertaken should your investments go wrong, and the time-frame you have set aside for each investment. Your philosophy can be adjusted to suit the current scenario. Having an investment philosophy prevents us from being overly-greedy or overly fearful.
10. Transactional type of investments.
For most of us, the only purpose we invest is to make money. After that, what next? We need to have a purpose for our investments. Why did we invest in stocks, unit trusts and property? To make money? Yes, but what’s the purpose behind that purpose? Your investments must be purpose-driven, for example, to clear debts, fund a comfortable retirement, or to send your kids to college. Remember, greed is not a purpose.
Joyce Chuah is a Financial Intelligence trainer and Certified Financial Planner who has been in the industry for 10 years.
Monday, March 23, 2009
Sold Bursa at RM5.05

Sold all my BURSA for RM5.05 that gotten at RM5 and make some tiny lunch money.
Friday, March 20, 2009
Received 4th Interim Dividend 3sen from ZHULIAN

Just gotten the 4th Interim Dividend of 3sen from Zhulian. Dividend has been paid on every quarter so far. Take a look of it div history.
Friday, March 13, 2009
Received Dividend From PBBANK-01 & IOICORP


Just received 25% div and share div of 1:35 from PBBANK-01, and 30% div from IOICORP. Take a look of their div history as well....
Subscribe to:
Posts (Atom)
